How to Read a Profit and Loss Statement
Looking for a tool?
Read a profit and loss statement in three passes, not top to bottom. First net profit — did the business make money at all. Then gross margin — does the work itself pay, before overhead. Then the trend across at least three periods — is the pattern improving or quietly rotting. Everything else on the page is detail that supports one of those three. Below: a worked quarter with every figure recomputed, what a healthy margin looks like (with the source), the six red flags, and the one thing a P&L never tells you.
This is the companion to how to build a profit and loss statement in Google Sheets. That one gets the rows and formulas right. This one is about what to do once the numbers are on the page.
The three passes, in order
| Pass | Number | The question it answers | What a bad answer means |
|---|---|---|---|
| 1 | Net profit | Did the business earn more than it spent? | Something is wrong — passes 2 and 3 tell you where |
| 2 | Gross margin | Does the work itself pay, before overhead? | A pricing or cost problem. Overhead cuts will not fix it |
| 3 | The trend | Is this month better or worse than the pattern? | A direction problem — act before it reaches the bottom line |
The order matters because it stops you fixing the wrong thing. A business with a 22% gross margin does not have an overhead problem no matter how carefully you audit the phone bill — it has a pricing problem, and pass 2 is where you see that.
A worked quarter
Here is one quarter for a solo contractor. Every figure is arithmetic you can redo, and the whole thing comes off two logs: money in, money out.
| Line | Amount | % of revenue |
|---|---|---|
| Revenue | $48,000.00 | 100.0% |
| Materials | $12,000.00 | 25.0% |
| Subcontracted labour | $4,000.00 | 8.3% |
| Cost of sales | $16,000.00 | 33.3% |
| Gross profit | $32,000.00 | 66.7% |
| Vehicle & fuel | $2,400.00 | 5.0% |
| Insurance | $1,500.00 | 3.1% |
| Tools & small equipment | $900.00 | 1.9% |
| Advertising | $750.00 | 1.6% |
| Accounting | $600.00 | 1.3% |
| Phone & software | $450.00 | 0.9% |
| Bank & card fees | $400.00 | 0.8% |
| Operating expenses | $7,000.00 | 14.6% |
| Net profit | $25,000.00 | 52.1% |
Gross profit is $48,000 − $16,000 = $32,000, so gross margin is
32,000 ÷ 48,000 = 66.7%. Net profit is $32,000 − $7,000 = $25,000, so
net margin is 25,000 ÷ 48,000 = 52.1%. A 52% net margin should make you suspicious rather
than pleased, and the next section is why.
The number that is missing: your own labour
On a sole-proprietor P&L the owner does not appear as an expense. Money you take out is a draw, not payroll, so it never reaches the page. That means net profit is really profit plus your wages, added together and labelled as profit — and it is the single most common misreading of a small business P&L.
Separate them. Say the owner worked 480 hours that quarter (40 hours a week for twelve weeks) and would pay someone $35.00 an hour, fully loaded, to do that work:
- Owner labour at market rate:
480 × $35.00 = $16,800.00 - Profit after paying yourself:
$25,000 − $16,800 = $8,200.00 - Real net margin:
8,200 ÷ 48,000 = 17.1% - What the owner actually earned per hour:
25,000 ÷ 480 = $52.08
17.1% is a genuinely healthy small business. 52.1% was an illusion created by unpaid labour. Both numbers
came from the same statement — the difference is whether you read it as an owner or as a bookkeeper.
And the $25,000 is not spendable either: at a
25–30% self-employed tax set-aside,
roughly $7,500 of it belongs to the IRS before you touch any of it.
Gross margin: the most diagnostic number on the page
Gross margin is what is left of every sales dollar after the cost of actually delivering the work — materials, subcontractors, the hours of anyone you pay to do the job. It answers a question net profit cannot: is the work priced correctly?
Two rules that make it useful rather than decorative:
- Only direct costs go above the gross profit line. Insurance, your vehicle, software and advertising are overhead — they stay below it. Mixing them in is the mistake that makes gross margin meaningless, because the number then moves for reasons that have nothing to do with pricing.
- Gross margin should be stable. A margin that drifts down three periods in a row means your costs rose and your prices did not. Nothing about overhead will fix that; only repricing the work will.
The quarter above: 66.7%. If the next quarter comes in at 61% on similar work, materials cost
you an extra 5.7% × revenue that nobody passed on to a customer. On $48,000 of revenue that
is $2,736 — more than the entire vehicle line, invisible unless you compute the margin.
What counts as a healthy margin
Be careful with benchmarks: most published margin tables are built from listed companies, whose cost structures look nothing like a one-person business. The best public dataset is NYU Stern's, compiled by Aswath Damodaran from 5,994 firms, data as of January 2026 (margin by sector):
| Sector | Gross margin | Net margin |
|---|---|---|
| Total market (all 5,994 firms) | 37.76% | 9.74% |
| Business & consumer services | 33.38% | 7.03% |
| Retail (general) | 33.18% | 5.61% |
| Restaurant / dining | 32.24% | 9.37% |
| Software (system & application) | 71.72% | 25.49% |
Use these as a shape, not a target. Two honest caveats. First, these firms pay their staff, so their net margin is after labour — which is why the 17.1% figure above (after paying the owner) is the one to compare, not the 52.1%. Second, a service business with almost no materials will always show a high gross margin and a modest net margin, while a materials-heavy trade shows the reverse. Comparing yourself to your own last four quarters is worth more than comparing yourself to a sector average.
Six red flags
| What you see | What it usually means | Where to look |
|---|---|---|
| Revenue up, gross profit flat | You bought the growth — discounting, or costs rising unnoticed | Cost of sales as a % of revenue, period by period |
| Gross margin down three periods running | Your prices are last year's; your costs are this year's | Supplier invoices vs. your quoted rates |
| One expense line growing faster than revenue | A subscription, a fee or a vehicle cost that scaled when it shouldn't have | That line as a % of revenue, not its dollar total |
| Net profit near zero and a large owner draw | The business is paying you a wage and returning nothing on top | Draws vs. net profit — see the labour section above |
| Healthy profit, empty bank account | Timing, not profitability | Unpaid invoices, loan principal, equipment bought outright |
| One spectacular month | A big invoice landed, not a step change | The quarter, then the rolling three-month average |
Why a P&L can show profit when there is no money
A profit and loss statement measures earning. A bank balance measures cash. Four things move one without the other:
- Invoiced but unpaid work. On an accrual basis the revenue is on the P&L the day you invoice; the cash arrives weeks later, or never.
- Loan principal. Repaying principal takes real cash and is not an expense — only the interest appears on the P&L.
- Equipment bought outright. A $6,000 machine is an asset. It leaves the bank in one go but reaches the P&L slowly, as depreciation, or under a Section 179-style election in one year.
- Owner draws. Money you take out reduces the bank and never touches the P&L at all.
This is why a P&L alone is not enough to run on. Pair it with a simple cash flow tracker: the P&L tells you whether the business model works, cash flow tells you whether you survive until it does.
How often, and against what
Monthly is the right cadence for reading, quarterly for deciding. A single month is too noisy — one large invoice or one insurance renewal distorts it — but waiting for the year end means finding problems eleven months after you could have fixed them. Read each month against the two before it, and make pricing or spending decisions on the quarter.
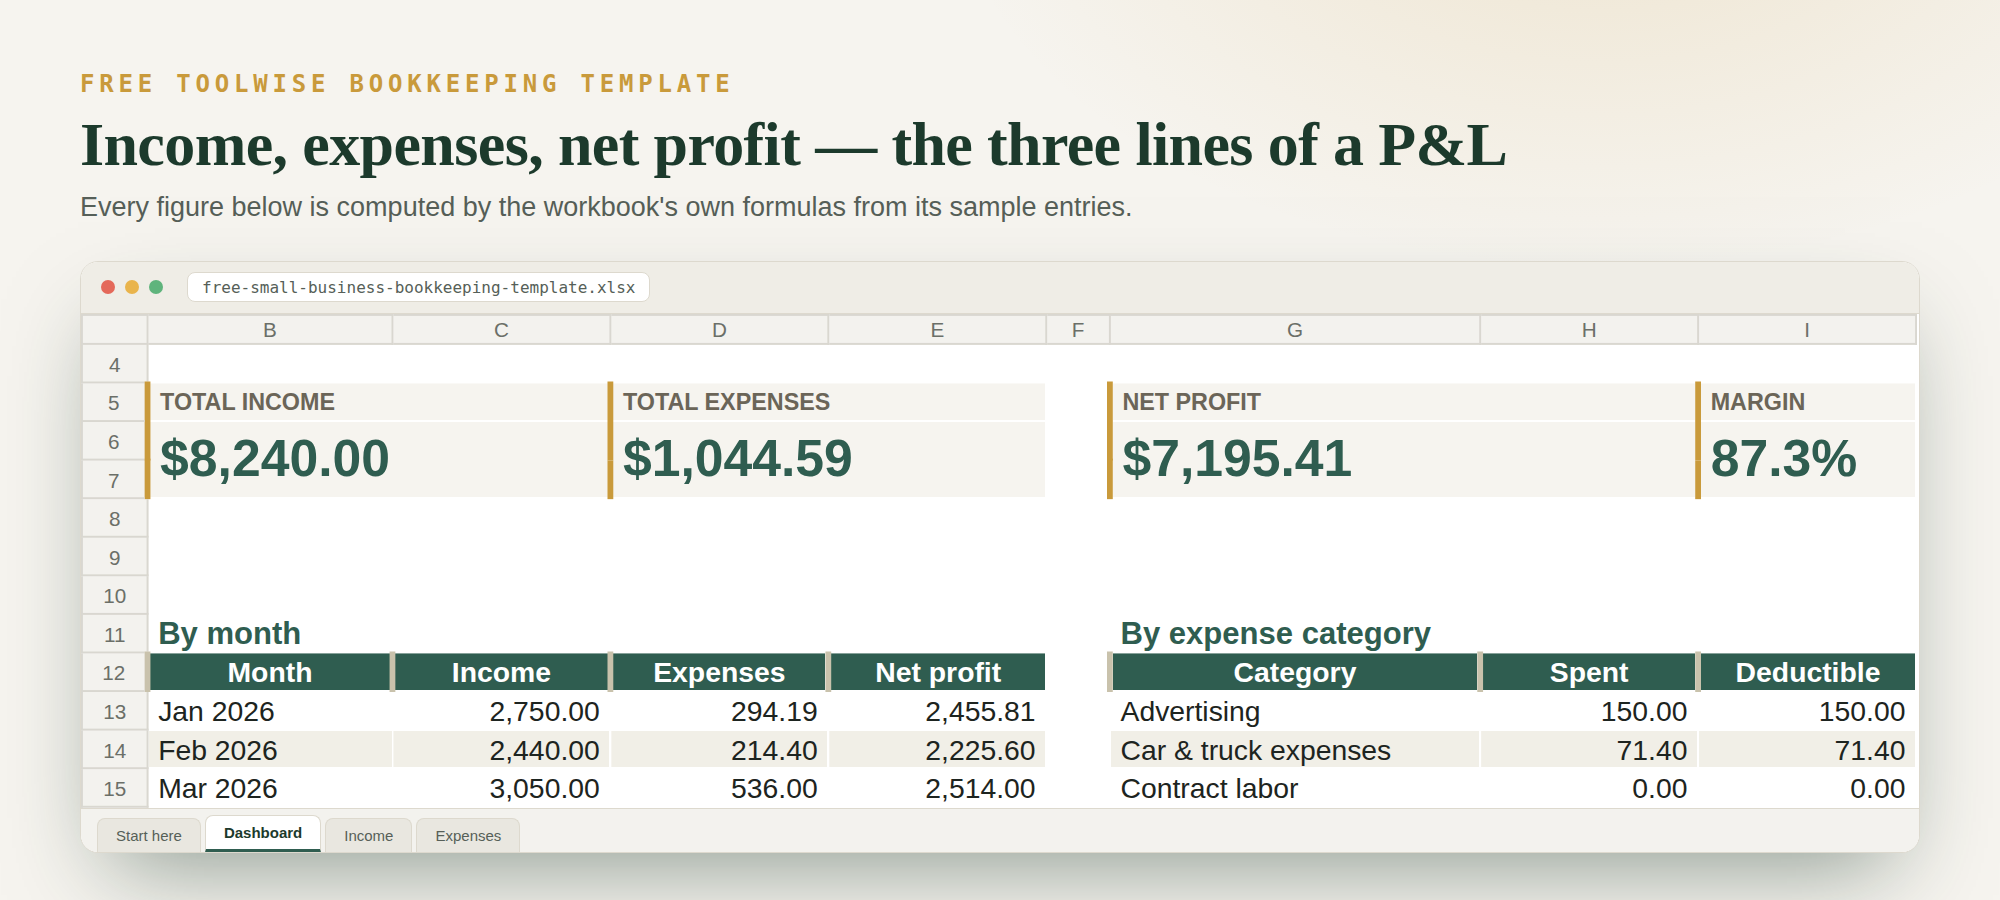
Set the statement up so the comparison is free rather than a monthly chore: one column per month, the same category rows down the side, and margins as formulas. That is exactly the layout in the income and expenses spreadsheet, and building it once is covered step by step in the P&L build guide.
Quick FAQ
What is a good profit margin for a small business?
There is no single number, but a useful reference point is the whole-market average from NYU Stern's January 2026 dataset of 5,994 firms: 37.76% gross margin and 9.74% net margin. For a one-person business, compare after subtracting what you would pay someone to do your own work — otherwise your net margin is flattered by unpaid labour.
What is the difference between gross profit and net profit?
Gross profit is revenue minus the direct cost of delivering the work (materials, subcontractors, job labour). Net profit is gross profit minus overhead (insurance, vehicle, software, advertising, accounting). Gross profit tells you whether the work is priced right; net profit tells you whether the business kept anything.
Why does my P&L show a profit when I have no money in the bank?
Usually unpaid invoices, loan principal repayments, equipment bought outright, or owner draws — all of which move cash without moving the P&L, or the reverse. Read the P&L alongside a cash flow tracker rather than instead of one.
Should my own pay appear on the profit and loss statement?
On a sole proprietorship it does not: draws are not payroll and never reach the statement. That is fine for filing, but for reading you should mentally subtract a market wage for your own hours before judging the net margin.
How often should I read my profit and loss statement?
Read it monthly against the two previous months, and make pricing or spending decisions on the quarter. A single month is too noisy to act on; a single year is too late to act on.
General guidance, not accounting or tax advice. Margin benchmarks are from NYU Stern's January 2026 dataset of listed companies and are a reference shape, not a target for a small business; the worked quarter uses illustrative figures chosen so every step can be reproduced by hand.
Related: build a P&L in Google Sheets · income and expenses spreadsheet · how much to set aside for taxes · cash flow tracking.